Trucking insurance is now one of the fastest-growing line items on a carrier's P&L, and most fleet owners feel it at every renewal. Understanding what you must carry, what drives your premium and what you can actually control is the difference between a manageable cost and a margin killer. This guide covers the basics of trucking insurance for small and mid-size carriers and the steps that tend to matter most at renewal.
What the Federal Minimum Requires
Under 49 CFR 387.9, for-hire carriers hauling non-hazardous property with vehicles of 10,001 pounds GVWR or more in interstate commerce must carry at least $750,000 in financial responsibility. Hazardous cargo raises the floor: $1,000,000 for oil and certain listed materials, and $5,000,000 for the most dangerous bulk categories. Many shippers and brokers ask for $1 million or more regardless, so treat $750,000 as the legal floor, not a business target. Remember that a lapse in required coverage can put your operating authority at risk, so never let a policy expire while you shop for a better rate.
The Core Policies Most Carriers Carry
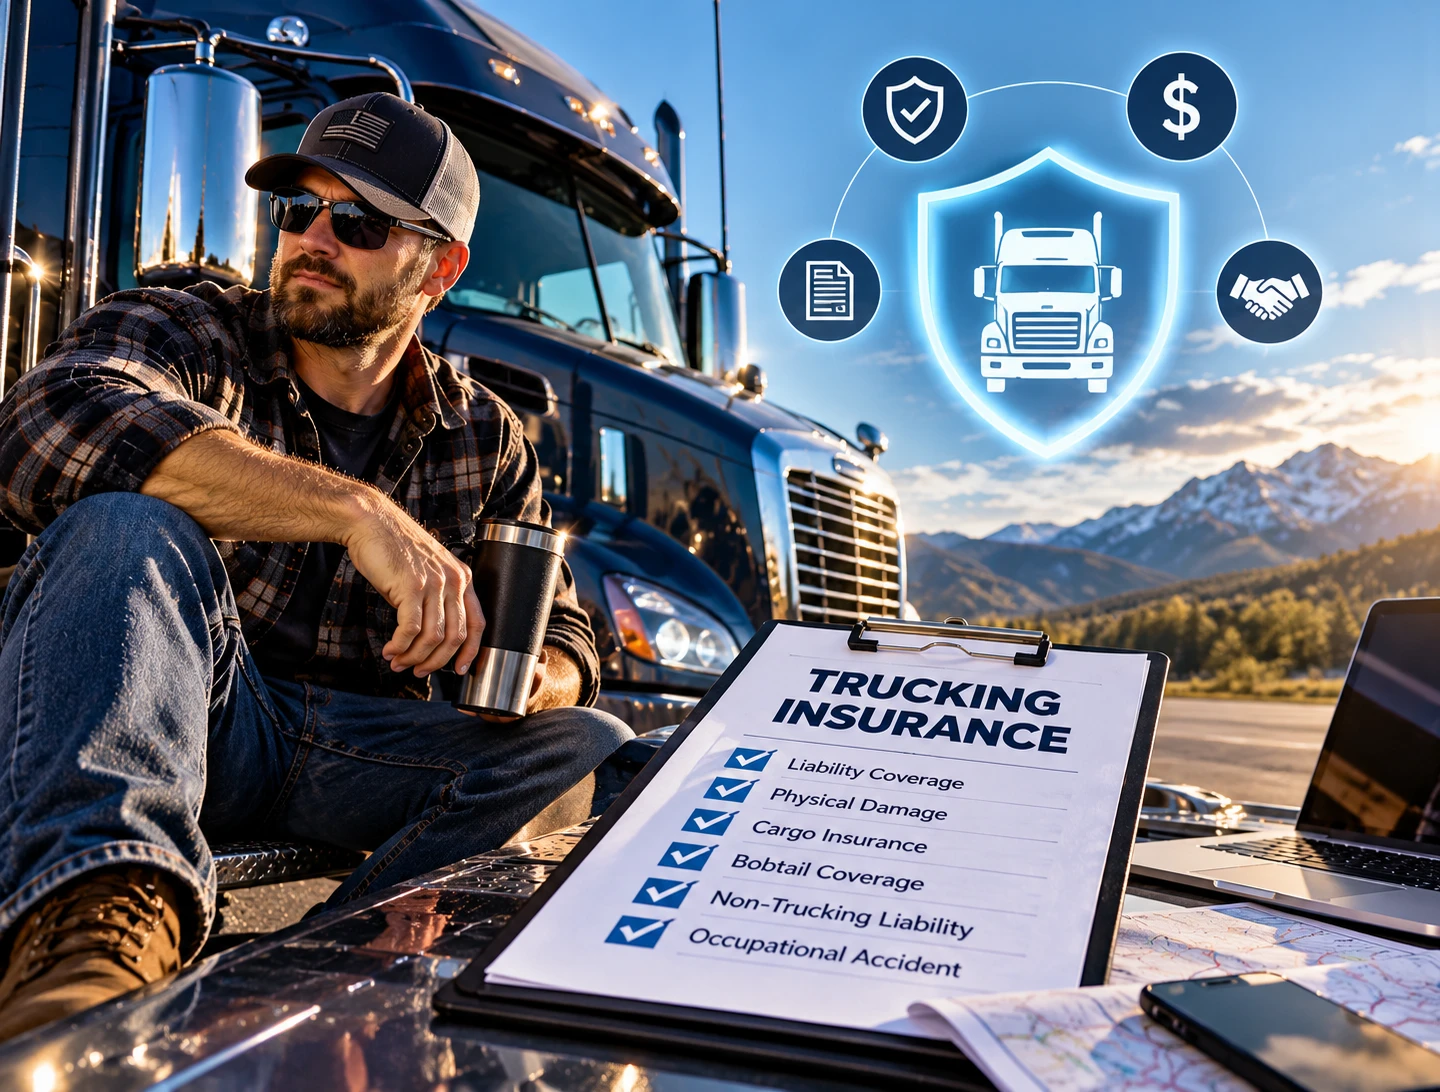
- Primary auto liability: pays for injury and property damage you cause to others. This is the largest piece of the premium.
- Physical damage: covers your tractors and trailers after a wreck, fire or theft.
- Motor truck cargo: covers the freight you haul. Many brokers require it.
- General liability: covers non-driving exposures such as your yard or terminal.
- Workers' compensation: required in most states for employees, which typically includes company drivers. Rules vary, so confirm with your state.
Ask your agent which of these apply to your operation. Do not assume that a quote covers everything on this list.
What Insurance Costs Right Now
According to the American Transportation Research Institute's operational-cost data as reported by FleetOwner, truck insurance premiums in the 2025 report averaged about $0.11 per mile, up 3.9% year over year, with the Northeast the most expensive region at roughly $0.12 and the Midwest the cheapest at about $0.10. The same coverage noted that Q1 2026 premiums were 6.4% higher than full-year 2025.
A quick worked example, using an assumption rather than a statistic: if a truck runs 100,000 miles a year, each cent per mile is $1,000 a year per truck. At roughly 11 cents per mile that is about $11,000 per truck annually. For a 20-truck fleet, a 6% increase would add around $13,000 a year. Use your own mileage and premium to replace these assumptions.
Why Premiums Keep Rising
ATRI's own report on insurance costs, covered by Trucking Info, pointed to litigation costs, growing insurer losses and broader "social inflation" in claim payouts as the main drivers, most of them outside your control. It also found that small fleets paid more than three times as much per mile as very large fleets. FleetOwner's summary of the more recent report adds that commercial auto insurance has been unprofitable for insurers in nearly every one of the last ten years. In other words, some of the increase is market-wide, and shopping alone will not make it disappear.
What You Can Control
Your premium reflects how an underwriter sees your risk. These are the levers carriers can actually pull:
- Driver quality and experience. Hire carefully, check MVRs and PSP reports, and keep your driver qualification files complete. Underwriters look at who is behind the wheel.
- Turnover. A constant stream of new drivers is a risk factor in itself. Stronger retention helps both costs and safety.
- Safety technology. ATRI reported that 92% of surveyed carriers added new safety technology as part of their response to rising costs. Cameras and telematics can help you coach drivers and defend claims.
- Deductibles and retention. ATRI noted that carriers commonly raise deductibles and self-insurance retention, or trim excess coverage above $1 million. These trade lower premium for more exposure, so only do this if your cash reserves can absorb a bad year.
- Your safety record. Watch your CSA scores and inspection results before renewal, not after.
Think in Total Cost of Risk
ATRI's central recommendation was for carriers to look at a "total cost of risk," meaning insurance premiums, deductibles, claims, safety investments and driver turnover together, rather than chasing the lowest quote. A cheap policy with high deductibles can cost far more after one serious accident. Start renewal conversations at least 90 days out, bring your safety data, and work with an agent who specializes in trucking.
Key Takeaways
- $750,000 is the federal minimum for most for-hire non-hazardous freight; many customers require more.
- Premiums averaged about 11 cents per mile in ATRI's 2025 data and were rising again in early 2026.
- Small fleets generally pay more per mile than large ones, so safety documentation matters even more.
- Driver hiring and retention directly affect how underwriters view you.
- Evaluate total cost of risk, not just the premium.
Insurance Starts With Who You Hire
Insurance cost and driver quality are connected: every new hire changes your risk profile. If your team is stretched thin, having a recruiting partner source and qualify drivers before they reach your orientation can help you hire more carefully, without rushing to fill a seat.
Need CDL-A Drivers? We Recruit Them for You.
CDL Transportation Group finds, qualifies, and delivers CDL-A OTR company drivers all the way to your orientation. No retainers, no setup fees, and no ad spend on you — you pay $2,000 per seated driver, split into two $1,000 payments, backed by a replacement guarantee.
Tell us how many drivers you need →
CDL Transportation Group | CDL-A OTR Driver Recruiting